You stroll into a bank to get a personal loan, feeling good about yourself, only to find out you’ve been rejected because of a bad credit score you didn’t even know about. It’s a maddening scenario that thousands of Indians land in each year and the saddest part is it is all preventable.
Your CIBIL score is among the most crucial figures in your financial life. It discreetly sits behind every loan approval, every credit card application and every interest rate that you’re offered. But most people never learn just how important it is until it’s working against them.
The good news? Checking your CIBIL score has never been easier — and your PAN card is the key to doing it in just a few minutes. In this guide, we’ll walk you through exactly how to check your CIBIL score online using your PAN card, why it matters, and what you can do to keep it healthy.
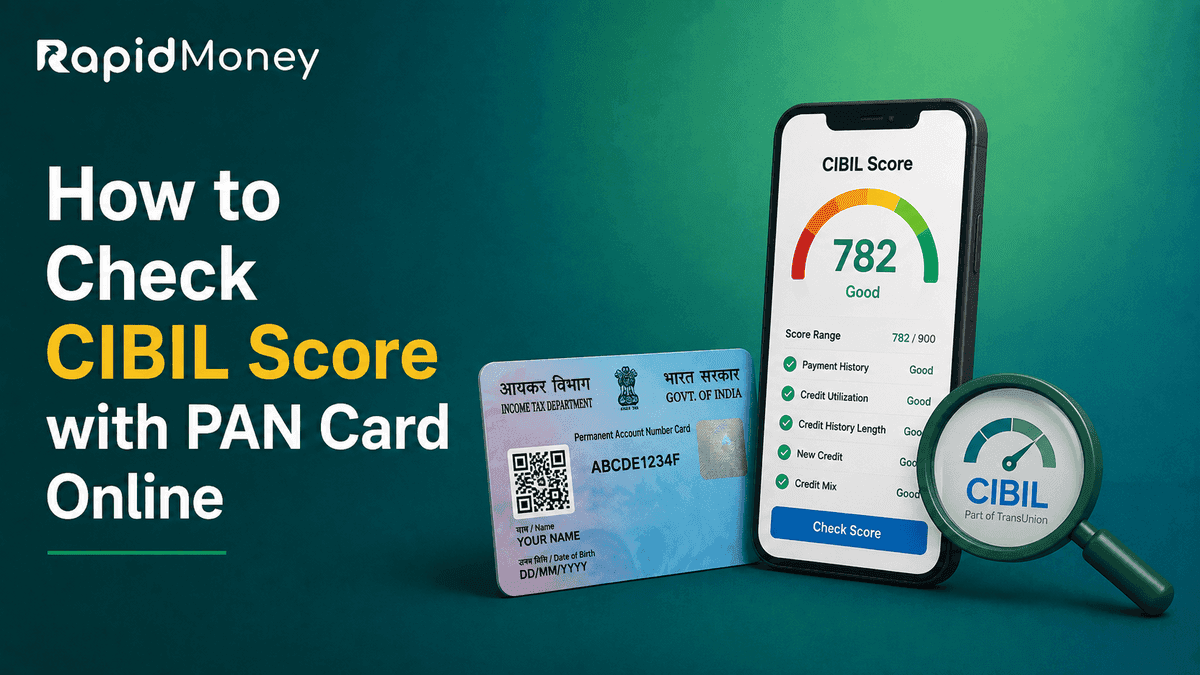
A CIBIL score is a three-digit number ranging from 300 to 900 that reflects your creditworthiness. It is generated by TransUnion CIBIL — India’s oldest and most widely used credit bureau — based on your credit history, repayment behaviour, outstanding debts, and the types of credit accounts you hold.
Think of it as your financial report card. Just as your school grades told teachers how well you understood your subjects, your CIBIL score tells lenders how reliably you handle borrowed money.
A score of 750 or above is generally considered the sweet spot. Most banks and NBFCs (Non-Banking Financial Companies) prefer lending to borrowers who fall in this range, as it signals a lower risk of default.
Your CIBIL score has a direct impact on several key financial decisions:
Yes, absolutely — and in fact, your PAN card is the most reliable way to retrieve your credit profile online.
Your Permanent Account Number (PAN) is a unique financial identity that is attached to all your credit operations like loans, credit cards and tax filings. The single most accurate technique to retrieve your credit report is, every lending institution sends your credit behaviour to credit bureaus using your PAN.
In case you do not have a PAN card, the system might not be able to identify you properly and the results might not be comprehensive or correct. This is why PAN is a vital field when you check your credit score on CIBIL and other third-party sites.
Besides your PAN, you will also need to provide:
A full walkthrough of the method:
Open your browser and log on to www.cibil.com. This is the official TransUnion CIBIL website and the best place to get your credit score. Steer clear of third-party sites that request too much personal information.
If you are a first time visitor, click on “Get Your Free CIBIL Score” or “Check Your Score” to start registration. Existing user Please login with your registered email id and password.
Enter your PAN card number carefully. Check and double-check every character. Just one inaccurate digit will prohibit the system from pulling your credit profile. You will also be required to give your full name (as per your PAN card), date of birth and contact data.
CIBIL will send an OTP to your registered mobile number after filling in your details. Please enter this OTP within the time window to verify your identity. That means no one else can see your credit information.
After successful verification, your CIBIL score will be displayed on the screen. You’ll see your three-digit score along with key factors that are influencing it — both positively and negatively.
You can also obtain your full credit report in PDF format. This report contains a full record of your credit accounts, current balances, payment history and any negative items such as defaults or settlements. Keep a copy of this report for your records.
Have the following handy before you get started:
Having these ready will make the process smooth and quick — typically done within 5 to 10 minutes.
One of the most common questions people have is whether checking their CIBIL score costs money. The answer is: not always.
TransUnion CIBIL offers one free credit score check per year under the RBI’s guidelines. You can access this directly on their official website. However, for more frequent access or a detailed report, they offer paid subscription plans.
Many banks now offer free credit score checks to their customers through internet banking or mobile apps. If you hold an account with HDFC Bank, SBI, Axis Bank, or ICICI Bank, check your net banking portal — there’s a good chance your credit score is just a click away, no additional registration needed.
There are platforms like Paisabazaar, BankBazaar, OneScore that give free CIBIL score check without charging a dime. These platforms pull your score from CIBIL or other bureaus and show it with personalised loan and credit card recommendations. Just be on a reliable and safe site when you share your details.
Many people treat credit score checks as a one-time task — something they do only before applying for a loan. But making it a regular habit can genuinely transform your financial health.
Benefits of checking your score regularly:
If your score isn’t where you want it to be, it’s important to understand why. Here are the most common culprits:
The encouraging thing about credit scores is that they’re not permanent. With consistent effort, you can gradually bring your score up. Here’s how:
Set up auto-pay or calendar reminders for all EMIs and credit card bills. And one missed payment can remain on your credit report for years. So make timely payments your number one financial priority.
Try to use no more than 30% of your available credit limit at any time. If you regularly come close to your limit, consider requesting a limit increase — this lowers your utilisation ratio without requiring you to spend less.
Don't submit all of your credit applications at once. Every challenging question will slightly lower your score. Lenders may become suspicious of a large number of enquiries in a short period of time. Before applying, find out if you are eligible.
You should review your report every 3-6 months. Check for errors such as accounts that don’t belong to you, inaccurate personal information, or payments that were marked late when they were paid on time. Resolve & Escalate CIBIL Issues.
The age of your credit history matters. An old credit card with a clean repayment record is a valuable asset. Don’t close it just because you don’t use it often — keep it active with a small occasional purchase.
Although the procedure is generally simple, you may run into the following difficulties:
Your CIBIL score is one of the most powerful tools in your financial toolkit — and checking it regularly is one of the simplest habits you can build to protect and grow your financial health. With your PAN card in hand, the entire process takes less than 10 minutes and can save you from unpleasant surprises when you need credit the most.
Whether you’re planning to apply for a home loan, a instant personal loan, or a premium credit card this year, start by knowing where you stand. Check your CIBIL score today, review your credit report carefully, and take the small but consistent steps that move you toward that excellent 750+ range.
Your financial future starts with a number — make sure it’s a good one.
Can I check my CIBIL score using only my PAN card?
Your PAN card is your primary identity but you will also need some basic personal information like your address and date of birth and a mobile number for OTP verification to complete the authentication procedure.
Is checking CIBIL score online free?
Yes, CIBIL provides one free score check per year. Several banking platforms and third-party apps like Paisabazaar also offer free credit score access anytime.
Does checking my own CIBIL score affect it?
No. When you check your own score, it’s called a “soft inquiry” and has absolutely no impact on your score. Only " hard inquiries” made by lenders when you apply for credit can affect your score.
How often should I check my CIBIL score?
Ideally, once every three to six months. Before applying for any loan or credit card, always check your score to assess your chances of approval.
What is the minimum CIBIL score required for a personal loan?
Most banks and NBFCs prefer a score of 700 or above for personal loans. Some lenders may approve loans for scores between 650 and 699, but usually at higher interest rates and with stricter terms.
Can I download my CIBIL report online?
Yes. After viewing your score on the CIBIL website, you have the option to download your full credit report as a PDF. This report contains a detailed history of all your credit accounts and payment behaviour.