Got some extra cash and wondering whether to pay off your personal loan early? You're not alone.
Every year, thousands of borrowers in India face the same dilemma: should they make a personal loan prepayment in small chunks, or close the entire loan at once through foreclosure?
This will impact your interest payments, credit score and monthly budget. This guide breaks down the two options in plain language, compares real numbers and helps you figure out which one actually saves more money in 2026.
Key Takeaways
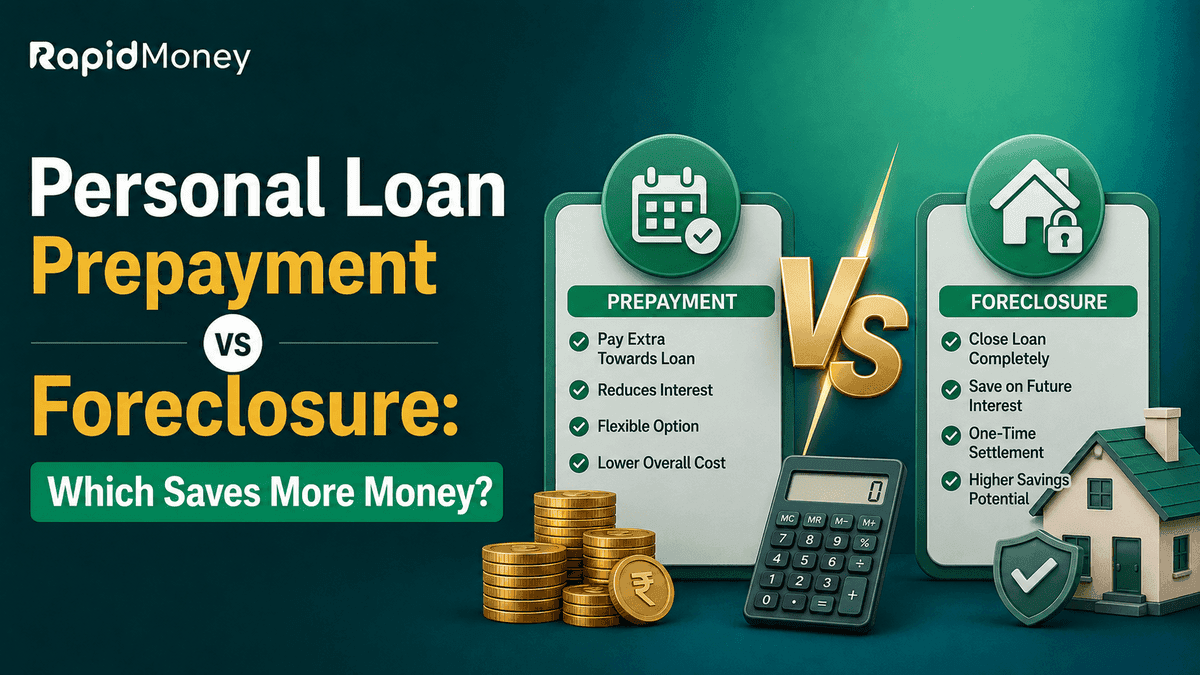
- Prepayment is when you pay more towards your loan while still paying your EMIs. Foreclosure is when you close the loan completely before the loan period gets over.
- Foreclosure frequently saves more in total interest because it gets rid of future interest all together.
- Most banks charge 2% to 5% foreclosure charges on the outstanding principal for personal loans, while RBI rules restrict such charges only on floating-rate loans to individual, non-business borrowers.
- Prepaying early in the loan tenure saves significantly more than prepaying near the end.
- Always compare the prepayment penalty against the interest you'll actually save before deciding.
What Is Personal Loan Prepayment?
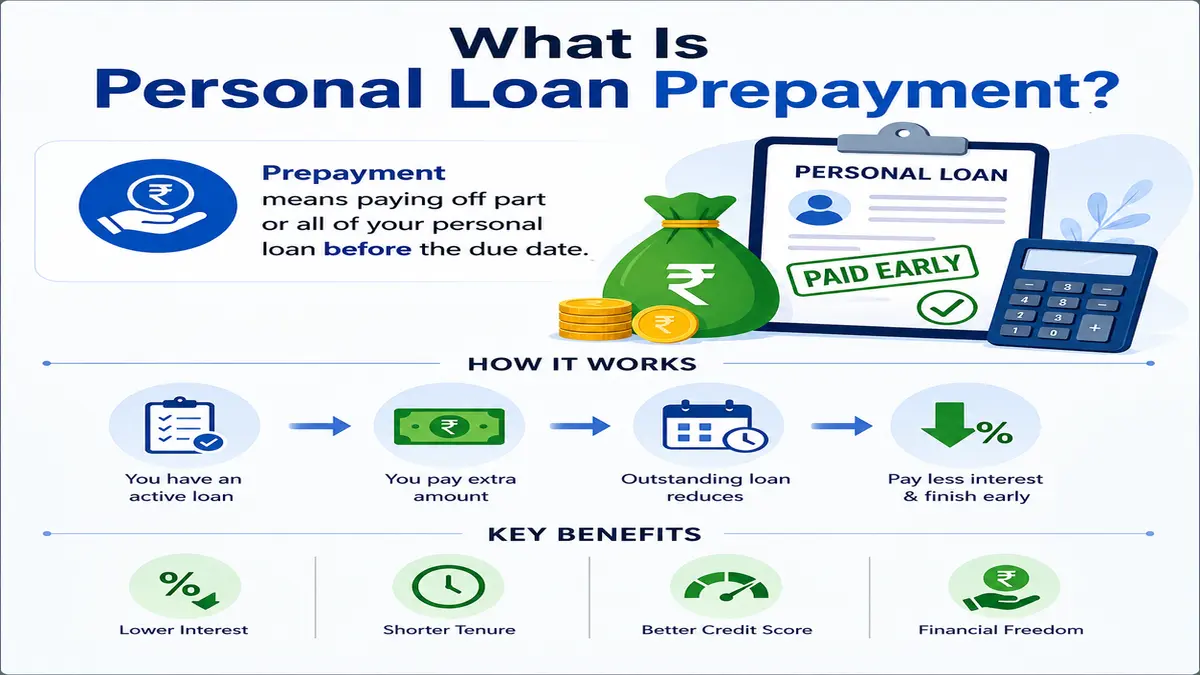
Personal loan prepayment is when you pay an extra amount over and above your regular EMI to reduce the outstanding principal.
You continue the loan, but with a smaller balance, which means less interest going forward.
Prepayment can be done partially — once, twice, or multiple times during the loan tenure — depending on your lender's policy.
Most banks and NBFCs permit partial prepayment after a lock-in period, which is generally 6 to 12 months from the date of disbursal.
 What Is Personal Loan Foreclosure?
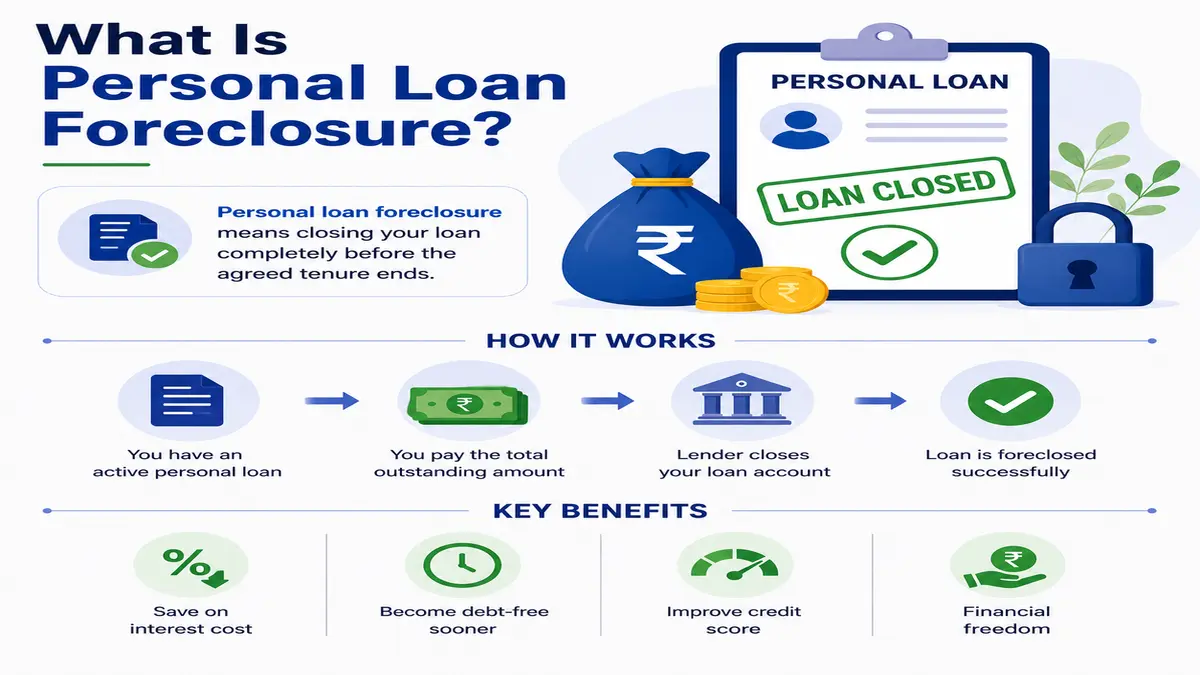
Foreclosure of loan is a situation where the entire outstanding loan amount is paid before the tenure of the loan is complete.
Once you foreclose, the loan account is closed permanently, and you stop paying EMIs altogether.
This is different from prepayment, which only reduces the balance while keeping the loan active.
Foreclosure is usually the better route when you have a lump sum — like a bonus, maturity amount, or inheritance — and want to be debt-free faster.
 Prepayment and Foreclosure: Key Differences
<table style="width:100%; border-collapse:collapse; font-family:Arial, sans-serif; font-size:15px; margin:20px 0; box-shadow:0 1px 4px rgba(0,0,0,0.1);">
<thead>
<tr style="background-color:#2c3e50; color:#ffffff; text-align:left;">
<th style="padding:12px 15px; border:1px solid #ddd;">Parameter</th>
<th style="padding:12px 15px; border:1px solid #ddd;">Prepayment</th>
<th style="padding:12px 15px; border:1px solid #ddd;">Foreclosure</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Loan Status</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Stays active</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Closed completely</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Amount Paid</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Partial, extra amount</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Full outstanding balance</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">EMI After Payment</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Reduces (or tenure shortens)</td>
<td style="padding:12px 15px; border:1px solid #ddd;">No more EMIs</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Interest Savings</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Moderate, ongoing</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Maximum, immediate</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Charges</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Usually 2%–4% on prepaid amount</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Usually 2%–5% on outstanding principal</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Best For</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Partial extra funds</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Lump sum availability</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Credit Score Impact</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Positive, gradual</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Positive, immediate "closed" status</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Flexibility</td>
<td style="padding:12px 15px; border:1px solid #ddd;">High, can repeat</td>
<td style="padding:12px 15px; border:1px solid #ddd;">One-time event</td>
</tr>
</tbody>
</table>
How Prepayment and Foreclosure Charges Work
Lenders charge a fee because early repayment reduces the interest income they expected to earn.
For fixed-rate personal loans, banks are free to charge foreclosure or prepayment penalties as per their policy.
No foreclosure or prepayment charges can be imposed by banks or NBFCs on floating-rate personal loans availed by individuals for non-business purposes.
Important Note: Most personal loans in India are fixed-rate, so this RBI relief mostly applies to floating-rate products.
Typical Charge Structure (2026)
<table style="width:100%; border-collapse:collapse; font-family:Arial, sans-serif; font-size:15px; margin:20px 0; box-shadow:0 1px 4px rgba(0,0,0,0.1);">
<thead>
<tr style="background-color:#2c3e50; color:#ffffff; text-align:left;">
<th style="padding:12px 15px; border:1px solid #ddd;">Lender Type</th>
<th style="padding:12px 15px; border:1px solid #ddd;">Foreclosure Charges</th>
<th style="padding:12px 15px; border:1px solid #ddd;">Prepayment Charges</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Public Sector Banks</td>
<td style="padding:12px 15px; border:1px solid #ddd;">2%–3% of outstanding principal</td>
<td style="padding:12px 15px; border:1px solid #ddd;">2%–3%</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Private Banks</td>
<td style="padding:12px 15px; border:1px solid #ddd;">3%–5% of outstanding principal</td>
<td style="padding:12px 15px; border:1px solid #ddd;">2%–4%</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">NBFCs/Fintech Lenders</td>
<td style="padding:12px 15px; border:1px solid #ddd;">2%–6% of outstanding principal</td>
<td style="padding:12px 15px; border:1px solid #ddd;">2%–5%</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Floating-rate loans (individual, non-business)</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Nil (as per RBI norms)</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Nil</td>
</tr>
</tbody>
</table>
<p style="font-family:Arial, sans-serif; font-size:13px; color:#666666; margin-top:-10px;"><em>Plus applicable GST on the charged amount.</em></p>
Eligibility and Rules For Prepayment/Foreclosure
<table style="width:100%; border-collapse:collapse; font-family:Arial, sans-serif; font-size:15px; margin:20px 0; box-shadow:0 1px 4px rgba(0,0,0,0.1);">
<thead>
<tr style="background-color:#2c3e50; color:#ffffff; text-align:left;">
<th style="padding:12px 15px; border:1px solid #ddd;">Criteria</th>
<th style="padding:12px 15px; border:1px solid #ddd;">Typical Requirement</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Minimum tenure completed</td>
<td style="padding:12px 15px; border:1px solid #ddd;">6–12 EMIs paid</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Loan status</td>
<td style="padding:12px 15px; border:1px solid #ddd;">No overdue payments</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Prepayment amount limit</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Often capped at 25%–50% of outstanding per year (varies by lender)</td>
</tr>
<tr style="background-color:#ffffff;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Foreclosure notice period</td>
<td style="padding:12px 15px; border:1px solid #ddd;">7–15 days advance intimation, as per lender</td>
</tr>
<tr style="background-color:#f9f9f9;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold;">Applicable loans</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Term loans; some flexi/overdraft loans have different rules</td>
</tr>
</tbody>
</table>
Lock-In Period Before Prepayment or Foreclosure
Most lenders want a lock-in period of 6 to 12 months from the date of loan disbursement.
You typically cannot foreclose or prepay during this period, even if you have the funds ready.
Check your loan sanction letter for the exact lock-in duration before planning your payoff strategy.
Step-by-Step Process to Prepay or Foreclose
- Check your loan agreement for prepayment/foreclosure clauses and applicable charges.
- Contact your lender via net banking, app, or branch to request a foreclosure/prepayment quote.
- Get the outstanding balance statement, with all applicable charges and gst.
- Make the payment through the lender's preferred mode (NEFT, cheque, or online portal).
- Collect the No Objection Certificate (NOC) and loan closure letter after payment.
- Verify your credit report after 30–45 days to confirm the loan shows as "closed."
Advantages and Disadvantages
Advantages of Prepayment
- Reduces interest burden without giving up all your savings at once
- Keeps some liquidity in hand
- Can be repeated multiple times during the tenure
- Shortens tenure or reduces EMI, your choice
Disadvantages of Prepayment
- Charges apply each time you prepay
- Loan is open till paid in full
- Some lenders limit the amount of prepayments every year
Advantages of Foreclosure
- Maximum interest savings
- Immediate debt freedom
- Improves debt-to-income ratio instantly
- Frees up loan eligibility for future borrowing
Disadvantages of Foreclosure
- Requires a large lump sum upfront
- Higher one-time charge on outstanding principal
- Depletes savings that could otherwise be invested
Common Mistakes to Avoid
- Ignoring the charges: Always remember to compute the net savings by subtracting the prepayment/foreclosure fees from the gross interest saved.
- Prepaying too late: Prepaying in the last year of tenure saves very little since most interest is already paid in early EMIs.
- Skipping the NOC: Not collecting the closure letter can cause issues with your credit report later.
- Using emergency funds: Never foreclose a loan by draining your entire emergency fund.
- Not comparing investment returns: If your investments earn more than your loan's interest rate, foreclosure may not always be the smartest move.
Case Study: Rohan's Loan Payoff Decision
Rohan had taken a personal loan of ₹4,00,000 at the rate of 13% for 4 years. In 18 months he got a bonus of Rs 1.5 lakh.
He had two choices: to partially payback ₹1,50,000 or wait and save more to foreclose the entire ₹2,80,000 debt six months later.
Using an online calculator, he found that prepaying immediately saved him more in interest than waiting, since interest accrues daily on the outstanding balance.
He chose to prepay right away and reduced his remaining tenure by over a year, saving roughly ₹28,000 in total interest.
Lesson: Acting sooner — even with a partial amount — often beats waiting for a "perfect" lump sum to foreclose.
FAQs
1. What is the difference between personal loan prepayment and foreclosure?
A prepayment is an extra payment on your loan while it is live, which reduces the amount you owe. Foreclosure is paying the full remaining balance all at once , and closing the loan forever . Prepayment just cuts the future interest . Foreclosure ends all interest immediately .
2. Which saves more money, prepayment or foreclosure?
Foreclosure frequently saves more overall interest because it pays off the whole loan sum at once. But if you can’t swing the full lump sum, regular partial prepayments still offer a considerable continuous saving throughout the life of the loan.
3. Are there charges for personal loan foreclosure in 2026?
Yes, most fixed-rate personal loans charge a foreclosure fee of 2% to 5% on the outstanding principal plus GST. In general, the RBI guidelines do not apply to floating-rate loans taken by individual, non-business borrowers.
4. Can I prepay my personal loan anytime?
Most of the lenders permit prepayment only after a lock in period of 6 to 12 months from the date of disbursement. Then, most lenders allow you to prepay many times, but some have limits on the amount or how often you can do it every year.
5. Does foreclosing a personal loan improve my credit score?
Yes, foreclosure can have a positive impact on your credit score. Foreclosure reduces your total debt load. It also improves your credit utilisation ratio. This loan account will appear as “closed” on your credit report, which is a good sign to lenders.
6. Is it better to prepay early or late in the loan tenure?
Prepayment saves far more money because interest is front-loaded in most EMI schemes. Most of the interest has been paid, so not much savings in prepaying in the last year.
7. Should I use my emergency fund to foreclose a personal loan?
It's generally not advisable to fully drain your emergency fund for foreclosure. Keep at least 3–6 months of expenses aside, and use surplus funds beyond that for prepayment or foreclosure.
8. How long does it take to close a loan after foreclosure payment?
Most Lenders take 7-15 working days to process the foreclosure and give the NOC shortly. Credit bureaux normally report the “closed” update 30 to 45 days after payment.
Conclusion
Choosing between personal loan prepayment vs foreclosure ultimately comes down to how much money you have available and how quickly you want to be debt-free.
Foreclosure generally saves more in total interest since it clears the entire outstanding balance at once, even after accounting for foreclosure charges.
Prepayment, on the other hand, offers flexibility for borrowers who can only spare extra funds occasionally rather than a full lump sum.
Whichever path you choose, run the numbers first — compare the interest you'll save against the charges you'll pay — before making the final call.
Ready to take action? Check your loan statement today, calculate your potential savings, and talk to your lender about the best repayment option for your situation.