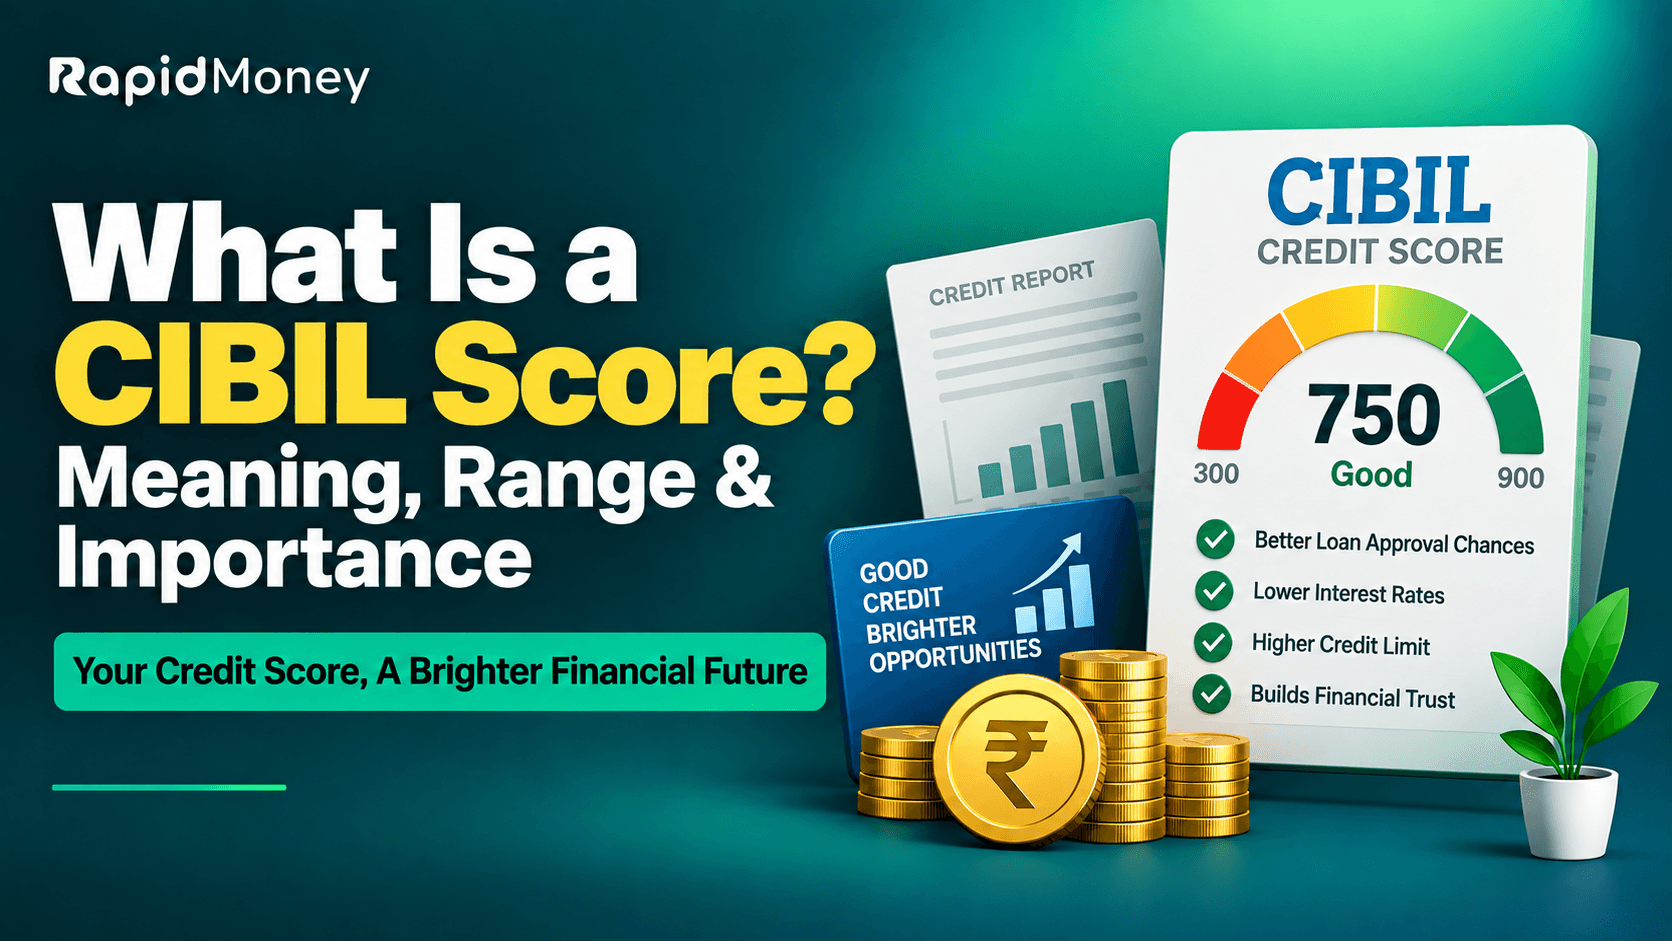
<div style="background-color: #e8f5e9; border-radius: 12px; padding: 24px 28px; margin: 20px 0;"><h2 style="color: #2e7d32; font-weight: 700; font-size: 20px; margin: 0 0 12px 0;">Quick Answer</h2><p tyle="margin: 0; color: #2c2c2c; line-height: 1.6;">A CIBIL score is a three digit number ranging between 300 and 900 that reflects your creditworthiness, based on your past loan and credit card repayment history. Generally, a score over 750 is an excellent score and increases your chances of getting a loan approved quickly.</p></div>
If you've ever applied for a loan or credit card, you've probably been asked about your CIBIL score. But what is CIBIL score, really, and why does it decide whether a bank says yes or no to you?
In simple terms, your CIBIL score is a number that lenders use to determine your creditworthiness. It's one of the first things a bank checks before approving your loan application.
Key Takeaways
- CIBIL Score: 300 to 900. The higher it is, the better.
- A score of 750 and above is considered good by most lenders.
- Your score is based on repayment history, credit usage, credit mix, and credit age.
- You can check your CIBIL score online for free once a year.
- A low score doesn't mean you can't get a loan — some lenders, including RapidMoney, look beyond just the score.
What Is CIBIL Score?
CIBIL score, short for Credit Information Bureau (India) Limited score, is a numerical summary of your credit behaviour. It's generated using data from your past loans, credit cards, and repayment patterns.
Think of it as a financial report card. Every time you take a loan or use a credit card, that activity gets recorded. Over time, this builds a credit history, and CIBIL converts that history into a single score.
This score helps banks and NBFCs to rapidly assess how risky it is to give you money. A higher score implies responsible borrowing, whereas a lower one raises red flags.
<style>.rm-also-read-link:hover{color:#3E6B14 !important;}</style><p style="background:#F2FAE7; border-left:4px solid #8DC63F; margin:28px 0; padding:16px 20px; font-size:16px; font-family:-apple-system,BlinkMacSystemFont,'Segoe UI',Arial,sans-serif; line-height:1.6; word-wrap:break-word;"><span style="font-weight:700; color:#4a4a4a;">Also Read</span><span style="color:#c7dfb0; padding:0 10px;">|</span><a href="https://www.rapidmoney.in/blogs/how-to-build-credit-from-scratch="\_blank" class="rm-also-read-link" style="color:#1a1a1a; text-decoration:none; font-weight:400;">How to Build Credit From Scratch<span style="color:#5C9A21; font-weight:700;">›</span></a></p>
Who Calculates the CIBIL Score?
The score is calculated by TransUnion CIBIL, India's oldest and most widely used credit information company. Credit bureaus are regulated by the (RBI) under the Credit Information Companies (Regulation) Act, 2005.
Banks, NBFCs, and other lenders report your loan and credit card data to CIBIL every month. CIBIL compiles this into your Credit Information Report (CIR), and your score is derived from it.
Important Note: CIBIL is not the only credit bureau in India. Experian and CRIF High Mark also generate similar scores, but CIBIL remains the most commonly referenced one by lenders.
CIBIL Score Range Explained
Your CIBIL score always falls between 300 and 900. Here's how lenders typically interpret different score ranges:
<table style="width:100%; border-collapse:collapse; font-family:Arial, sans-serif; font-size:15px; margin:20px 0;">
<thead>
<tr>
<th style="background-color:#2c3e50; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">CIBIL Score Range</th>
<th style="background-color:#2c3e50; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">Category</th>
<th style="background-color:#2c3e50; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">What It Means for You</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#fdecea;">
<td style="padding:12px 15px; border:1px solid #ddd;">300–549</td>
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#c0392b;">Poor</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Loan approval very unlikely; high risk</td>
</tr>
<tr style="background-color:#fff8e1;">
<td style="padding:12px 15px; border:1px solid #ddd;">550–649</td>
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#b8860b;">Fair</td>
<td style="padding:12px 15px; border:1px solid #ddd;">May get loans, but at higher interest rates</td>
</tr>
<tr style="background-color:#e8f5e9;">
<td style="padding:12px 15px; border:1px solid #ddd;">650–749</td>
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#2e7d32;">Good</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Reasonable approval chances</td>
</tr>
<tr style="background-color:#e3f2fd;">
<td style="padding:12px 15px; border:1px solid #ddd;">750–900</td>
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#1565c0;">Excellent</td>
<td style="padding:12px 15px; border:1px solid #ddd;">Fast approval, better interest rates</td>
</tr>
</tbody>
</table>
A score of 750 or above is considered the sweet spot for getting approved quickly and at competitive interest rates.
How Is CIBIL Score Calculated?
CIBIL doesn't just pick a random number. It weighs several factors from your credit history to arrive at your score.
Here's a general breakdown of what influences it:
- Repayment history (around 30%): Paying EMIs and credit card bills on time matters most.
- Credit utilisation (around 25%): How much of your available credit limit you're using.
- Credit age (around 15%): Older credit accounts in good standing help your score.
- Credit mix (around 10%): A healthy balance of secured (like home loans) and unsecured (like personal loans) credit.
- Recent credit enquiries (around 20%): Applying for several loans or credit cards at once can also hurt your score.
Expert Tip: Even a single missed EMI payment can pull your score down noticeably, so setting up auto-debit for repayments is a smart habit.
Why Does CIBIL Score Matter for Loans?
Your CIBIL score directly affects three things when you apply for credit:
- Approval chances — A good score means faster, smoother approval.
- Interest rate — Higher scores often get lower interest rates.
- Loan amount — Strong scores may mean borrowers are able to borrow a larger loan amount.
For instant personal loans, especially smaller ticket-size loans, some lenders also factor in income stability and repayment capacity alongside the score, so a moderate score doesn't always mean rejection.
Does CIBIL Score Affect Instant Personal Loan Approval?
Yes, but not in isolation. For instant personal loans, digital lenders often combine your CIBIL score with real-time factors like income, existing obligations, and repayment behaviour on other apps. This is why some borrowers with an average score can still get approved for small, short-tenure loans.
<style>.rm-also-read-link:hover{color:#3E6B14 !important;}</style>
<table style="width:100%; border-collapse:collapse; background:#F2FAE7; border-left:4px solid #8DC63F; margin:28px 0;"><tr><td style="padding:16px 20px; font-size:16px; font-family:-apple-system,BlinkMacSystemFont,'Segoe UI',Arial,sans-serif; line-height:1.6; white-space:nowrap;"><span style="font-weight:700; color:#4a4a4a;">Also Read</span><span style="color:#c7dfb0; padding:0 10px;">|</span><a href="https://www.rapidmoney.in/blogs/does-checking-cibil-score-reduce-credit-score" target="\_blank" class="rm-also-read-link" style="color:#1a1a1a; text-decoration:none; font-weight:400;">Does Checking Your CIBIL Score Reduce It?<span style="color:#5C9A21; font-weight:700;">›</span></a></td></tr></table>
How to Check Your CIBIL Score for Free
You're entitled to one free CIBIL report per year directly from TransUnion CIBIL. Here's how to check it:
- Visit the official CIBIL website.
- Click on "Get Your Free CIBIL Score."
- Enter your PAN, date of birth, and contact details.
- Verify your identity via OTP.
- View and download your credit score and report.
Pro Tip: Avoid entering your CIBIL details on unverified third-party websites. Stick to official platforms or RBI-regulated financial apps to protect your data.
How to Improve a CIBIL Score
If your score isn't where you'd like it to be, don't worry — it's fixable over time. Here's what helps:
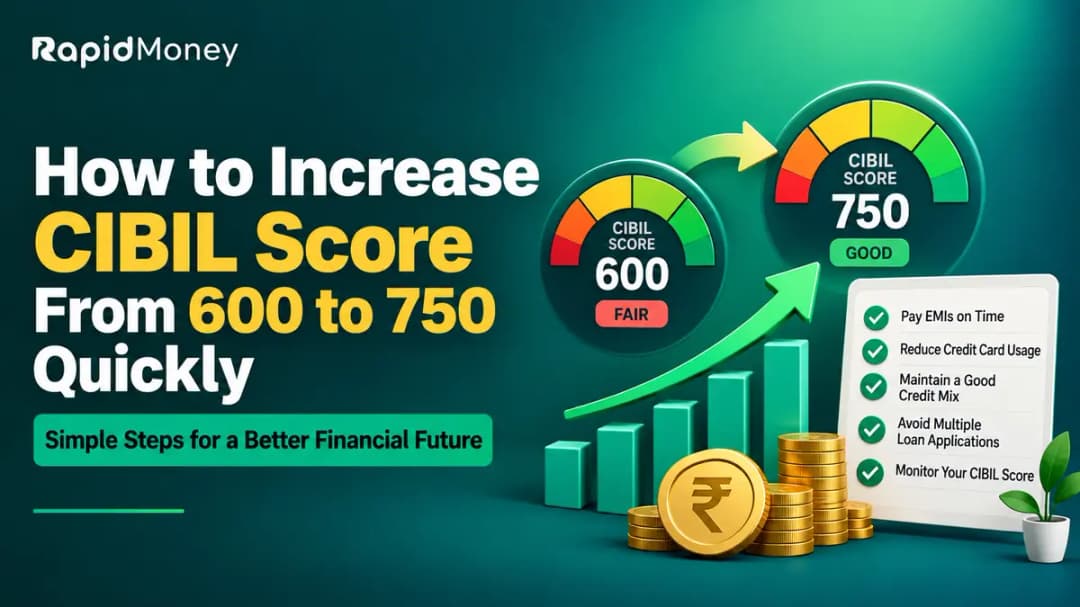
- Pay EMIs and credit card bills on schedule or before due date, every time.
- Keep credit utilisation below 30% of your total limit.
- Avoid applying for multiple loans or cards within a short period.
- Don't close old credit accounts; a longer credit history helps.
- Check your credit report often for inaccuracies and get them corrected.
Improvement isn't instant. Most people see a noticeable change within 3 to 6 months of consistent, disciplined repayment behaviour.
<style>.rm-also-read-link:hover{color:#3E6B14 !important;}</style>
<table style="width:100%; border-collapse:collapse; background:#F2FAE7; border-left:4px solid #8DC63F; margin:28px 0;"><tr><td style="padding:16px 20px; font-size:16px; font-family:-apple-system,BlinkMacSystemFont,'Segoe UI',Arial,sans-serif; line-height:1.6; white-space:nowrap;"><span style="font-weight:700; color:#4a4a4a;">Also Read</span><span style="color:#c7dfb0; padding:0 10px;">|</span><a href="https://www.rapidmoney.in/blogs/how-to-increase-cibil-score-from-600-to-750" target="\_blank" class="rm-also-read-link" style="color:#1a1a1a; text-decoration:none; font-weight:400;">How to Increase CIBIL Score From 600 to 750<span style="color:#5C9A21; font-weight:700;">›</span></a></td></tr></table>
Frequently Asked Questions
1. What is CIBIL score in simple words?
Your CIBIL score is a 3 digit figure between 300 and 900 that indicates how reliably you have returned your prior loans and credit card dues. It is used by lenders to decide whether to lend you money and, if so, at what rate.
2. What is a good CIBIL score?
CIBIL score above 750 is considered very good. It improves your chances of fast loan approval and often gets you better interest rates compared to a lower score.
3. Can I get a loan with a low CIBIL score?
Yes, some lenders still approve loans with a lower score (particularly for smaller loan amounts) but the interest rates may be higher. The score is taken into account together with the income stability and the payback capabilities.
4. How often is CIBIL score updated?
CIBIL score is typically updated once a month, as banks and NBFCs report your account activity to the bureau on a monthly basis.
5. Is checking my own CIBIL score bad for my credit?
No. Checking your own CIBIL score is a "soft enquiry" and does not affect your score. Only "hard enquiries," made when lenders check your score for a loan application, can have a minor impact.
6. How long does bad credit history stay on my CIBIL report?
Negative information, such missed payments or defaults, can show on your credit report for up to 7 years, though its impact on your score reduces over time with good repayment behaviour.
7. What is the full form of CIBIL?
CIBIL stands for Credit Information Bureau (India) Limited, one of India's four RBI-licensed credit information companies.
8. Does having no credit history mean a bad CIBIL score?
Not exactly. If you've never taken a loan or credit card, you may have no CIBIL score at all (often shown as -1 or NA) rather than a poor one, since there's simply no data to calculate it.
9. How can I increase my CIBIL score quickly?
The fastest way to see an improvement is to pay all your EMIs and bills on time, keep your credit utilization low and not apply for multiple loans at the same time. Usually within a few months, you can see a difference.
10. Does CIBIL score affect instant personal loan approval?
Yes, it’s one of the primary things lenders look at but with fast personal loans, income and repayment behaviour on other platforms are often assessed alongside your score, not in isolation.
Conclusion
So, what is CIBIL score at the end of the day? It's basically a number that tells lenders how responsible you've been with credit in the past. The higher, the easier to get loans approved swiftly and at better terms.
The good news is that your CIBIL score isn't fixed forever. With timely repayments and smart credit habits, you can improve it steadily over time.
If you're ready to apply for a quick, hassle-free personal loan regardless of where your score currently stands, apply with RapidMoney today and get instant approval in minutes.