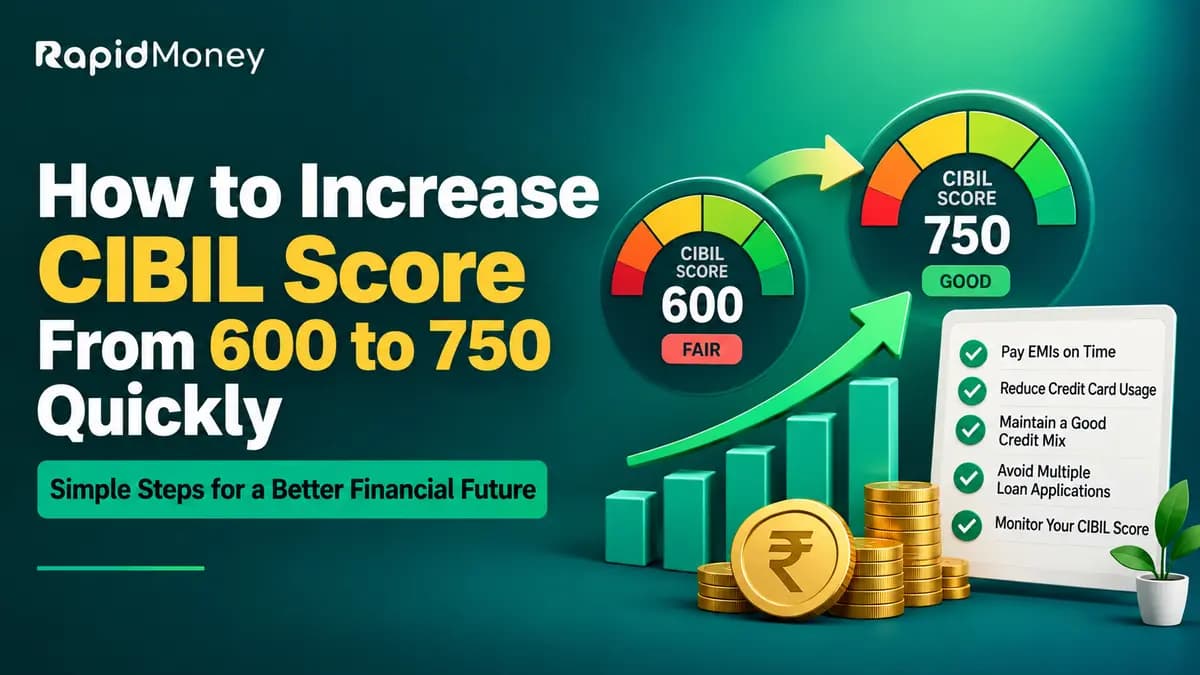
<div style="background-color: #e8f5e9; border-radius: 12px; padding: 24px 28px; margin: 20px 0;"><h2 style="color: #2e7d32; font-weight: 700; font-size: 20px; margin: 0 0 12px 0;">Quick Summary</h2><p style="margin: 0; color: #2c2c2c; line-height: 1.6;">To increase CIBIL score from 600 to 750, pay every EMI and credit card bill on time, keep credit utilisation under 30%, don’t apply for several loans, keep a good mix of secured and unsecured credit, and read your credit report each month to make sure there are no mistakes. </p></div>
A CIBIL score of 600 could feel like a closed door. Loans are denied. If you are authorised at all . Credit cards have hefty interest rates . It’s frustrating, especially when you’re aware you can manage credit properly.
The good news? A score of 600 is not permanent. Thousands of Indians move from 600 to 750+ every year, and you can too.
This guide breaks down exactly how to increase CIBIL score from 600 to 750 using seven practical, proven steps. No gimmicks, no shortcuts that backfire — just what actually works, backed by how credit bureaus calculate your score in 2026.
<div style="max-width:850px;margin:25px auto;padding:14px 18px;background:#1b1d22;border-radius:14px;display:flex;flex-wrap:wrap;align-items:center;gap:15px;font-family:Arial,sans-serif;box-shadow:0 4px 12px rgba(0,0,0,.15);"><div style="display:flex;align-items:center;gap:12px;flex:5 1 260px;min-width:0;"><div style="width:42px;height:42px;background:#233a18;border-radius:10px;display:flex;align-items:center;justify-content:center;color:#8CFF00;font-size:20px;font-weight:bold;flex-shrink:0;">⚡</div><div><div style="font-size:11px;font-weight:700;color:#8CFF00;text-transform:uppercase;letter-spacing:1px;">Instant Approval</div><div style="font-size:20px;font-weight:700;color:#fff;line-height:1.3;">Get Personal loan upto <span style="color:#8CFF00;">₹15,000</span></div></div></div><a href="https://web.rapidmoney.in/borrower/login?utm\\\_source=seo\\\&utm\\\_medium=blog\\\&utm\\\_campaign=cibil-score-from-600-750\\\&utm\\\_content=cta\\\_banner" target="\\\_blank" rel="noopener noreferrer" style="background:#8CFF00;color:#111;text-decoration:none;padding:10px 22px;border-radius:10px;font-size:15px;font-weight:700;text-align:center;flex:1 1 160px;box-sizing:border-box;">Apply Now →</a></div>
Key Takeaways
- A CIBIL score above 750 unlocks better loan approvals and lower interest rates.
- Payment history contributes the most to your score, so timely EMIs matter most.
- Keeping credit utilisation below 30% can significantly boost your score.
- Avoid applying for multiple loans or cards within a short period.
- Most people can improve their score meaningfully within 4 to 8 months.
- Regularly checking your credit report may help you detect any mistakes and repair them early on.
Why a CIBIL Score of 750 Matters
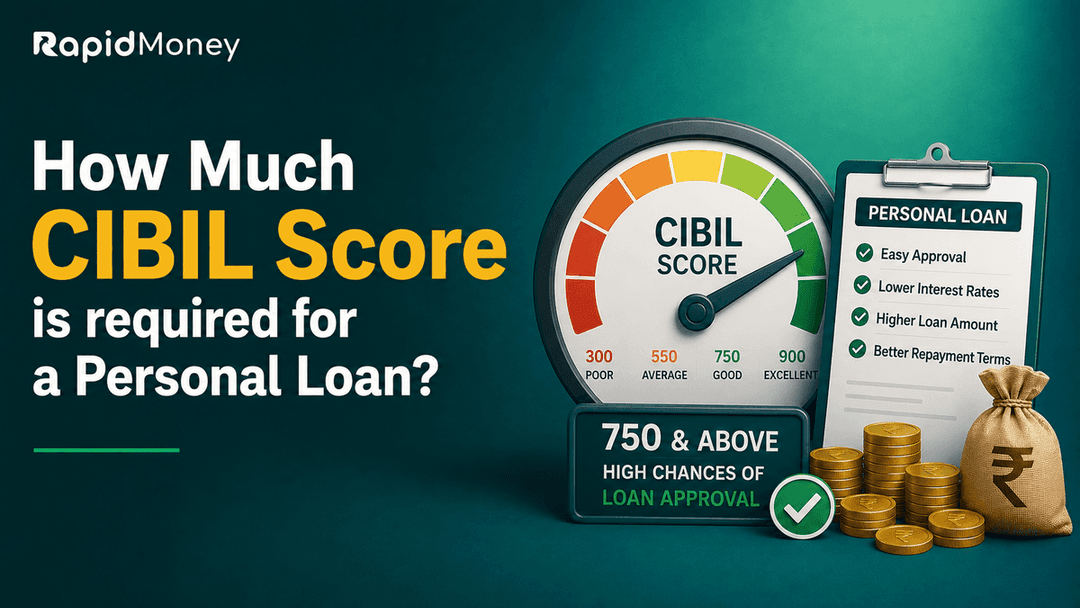
In India, a score of over 750 is widely regarded as the threshold for “good” credit. This criterion is used by banks and NBFCs to approve loans swiftly and offer the greatest interest rates.
Here's what changes once you cross that line:
<table style="width:100%; border-collapse:collapse; font-family:Arial, Helvetica, sans-serif; font-size:15px; margin:20px 0;">
<thead>
<tr>
<th style="background-color:#1f4e79; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">Score Range</th>
<th style="background-color:#1f4e79; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">What It Means for You</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#fdecea;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#c0392b;">300–579</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Poor. Loan approvals are rare; high risk category.</td>
</tr>
<tr style="background-color:#fff8e1;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#b8860b;">580–669</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Fair. Approvals possible but with higher interest.</td>
</tr>
<tr style="background-color:#e8f4fd;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#2471a3;">670–739</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Good. Better approval odds, moderate rates.</td>
</tr>
<tr style="background-color:#e9f7ef;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#1e8449;">750–900</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Excellent. Fast approvals, lowest interest rates.</td>
</tr>
</tbody>
</table>
If you're aiming to improve CIBIL score from 600 to 750, you're essentially moving from the "fair" bracket into "excellent" — a jump that directly affects your EMI amounts for years.
What Affects Your CIBIL Score
It’s good to know what really pushes the needle before fixing. CIBIL (TransUnion CIBIL) uses many weighted elements to determine your score.
- Payment history (35%): Late payments hurt the most.
- Credit utilisation (30%): How much of your available credit you use.
- Credit age (15%): Longer credit history builds trust.
- Credit mix (10%): A mix of secured and unsecured loans helps.
- New credit enquiries (10%): Frequent applications signal risk.
Knowing this breakdown makes the next section much easier to act on.
<style>.rm-also-read-link:hover{color:#3E6B14 !important;}</style>
<p style="background:#F2FAE7; border-left:4px solid #8DC63F; margin:28px 0; padding:16px 20px; font-size:16px; font-family:-apple-system,BlinkMacSystemFont,'Segoe UI',Arial,sans-serif; line-height:1.6; word-wrap:break-word;"><span style="font-weight:700; color:#4a4a4a;">Also Read</span><span style="color:#c7dfb0; padding:0 10px;">|</span><a href="https://www.rapidmoney.in/blogs/does-checking-cibil-score-reduce-credit-score" target="\_blank" class="rm-also-read-link" style="color:#1a1a1a; text-decoration:none; font-weight:400;">Does Checking your Cibil Score reduce it<span style="color:#5C9A21; font-weight:700;">›</span></a></p>
7 Proven Ways to Increase CIBIL Score From 600 to 750
1. Pay Every EMI and Credit Card Bill on Time
This is, by far, the single biggest lever you have. Even one missed payment can pull your score down significantly.
Set up an auto-debit for each due date or a calendar reminder. If your cash flow is tight, pay at least the minimal amount due on the due date and then pay off the balance immediately.
Pro Tip: Paying a few days before the due date, rather than exactly on it, protects you from bank processing delays.
2. Keep Credit Utilisation Below 30%
Credit usage is how much of your credit limit you are using. If your card limit is ₹1,00,000 and you consistently spend ₹80,000, that's a red flag to lenders.
Try to keep spending under 30% of your total limit. If that's difficult, consider requesting a credit limit increase, but don't use the extra room.
Example: On a ₹50,000 limit, aim to keep your outstanding balance under ₹15,000 at any time.
3. Avoid Multiple Loan or Credit Card Applications
Every time you apply for credit, the lender runs a "hard enquiry" on your report. Too many enquiries in a short span make you look credit-hungry, which lowers your score.
Space out applications by at least 3 to 6 months, and only apply when you genuinely need the credit.
4. Maintain a Healthy Credit Mix
Too much credit card (unsecured debt) isn't good. Including secured loans, like a car loan or a small personal loan that you’re successfully repaying, demonstrates lenders you’re able to handle diverse types of credit responsibly.
You don't need to take a loan just to "improve mix" — but if you already have one, manage it well instead of closing it early.
5. Don't Close Old Credit Cards
It's tempting to close an old card once you stop using it, but this will decrease your credit history and lower your overall available limit and both of them can damage your score.
Instead, keep the card active with a small, occasional transaction and pay it off immediately.
6. Check Your Credit Report for Errors Every Month
Errors happen more often than people realise — a loan marked as unpaid when it's closed, or an account that isn't even yours. These mistakes can silently drag your score down.
Get your report from CIBIL, Experian or CRIF High Mark at least once a month and raise disputes for any mistakes immediately.
Important Note: You're entitled to one free credit report per bureau per year in India; some platforms offer more frequent free checks.
7. Settle Outstanding Dues and Avoid Settlements Marked "Settled"
If you have old dues, pay them off in full rather than opting for a "settlement," which the lender reports differently and can hurt your score for years.
Clearing dues completely, even old small ones, sends a strong signal of reliability to future lenders.
How Long Does It Take to Improve Your CIBIL Score
There's no fixed timeline, but here's a realistic expectation based on consistent effort.
<table style="width:100%; border-collapse:collapse; font-family:Arial, Helvetica, sans-serif; font-size:15px; margin:20px 0;">
<thead>
<tr>
<th style="background-color:#1f4e79; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">Timeframe</th>
<th style="background-color:#1f4e79; color:#ffffff; padding:12px 15px; text-align:left; border:1px solid #ddd;">Expected Progress</th>
</tr>
</thead>
<tbody>
<tr style="background-color:#fdecea;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#c0392b;">1–2 months</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Minor uptick if you clear overdue payments</td>
</tr>
<tr style="background-color:#fff8e1;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#b8860b;">3–4 months</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Noticeable improvement with on-time payments and low utilisation</td>
</tr>
<tr style="background-color:#e8f4fd;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#2471a3;">5–8 months</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Significant jump, often 50–100+ points</td>
</tr>
<tr style="background-color:#e9f7ef;">
<td style="padding:12px 15px; border:1px solid #ddd; font-weight:bold; color:#1e8449;">9–12 months</td>
<td style="padding:12px 15px; border:1px solid #ddd; color:#333333;">Score can stabilise near or above 750 with sustained discipline</td>
</tr>
</tbody>
</table>
Individual results vary depending on your starting score, existing debt, and how promptly you act on the steps above.
<style>.rm-also-read-link:hover{color:#3E6B14 !important;}</style>
<p style="background:#F2FAE7; border-left:4px solid #8DC63F; margin:28px 0; padding:16px 20px; font-size:16px; font-family:-apple-system,BlinkMacSystemFont,'Segoe UI',Arial,sans-serif; line-height:1.6; word-wrap:break-word;"><span style="font-weight:700; color:#4a4a4a;">Also Read</span><span style="color:#c7dfb0; padding:0 10px;">|</span><a href="https://www.rapidmoney.in/blogs/how-to-improve-your-cibil-score-before-applying-for-a-loan" target="\_blank" class="rm-also-read-link" style="color:#1a1a1a; text-decoration:none; font-weight:400;">How to Imrpove Cibil score before applying for personal loan<span style="color:#5C9A21; font-weight:700;">›</span></a></p>
Common Mistakes That Slow Down Score Improvement
- Applying for a new loan while trying to fix your score
- Making only the minimum payment every month
- Ignoring your credit report until you need a loan
- Closing your oldest credit card
- Co-signing loans without tracking the primary borrower's payments
Avoiding these mistakes is just as important as following the seven steps above.
FAQs
1. How to Improve CIBIL Score Fast From 600 to 750?
Pay all EMIs and payments on time, keep credit utilisation under 30%, avoid new loan applications and check your credit report for inaccuracies monthly. With consistent discipline , you can expect results in 4-8 months
2. Is a CIBIL score of 600 bad?
A score of 600 is in the “fair” range. It’s hardly the worst score you can have, but it might limit your loan selections and often lead to higher interest rates. Improving it gives access to better financial products.
3. How much can a CIBIL score improve in one month?
It varies, but clearing overdue payments or fixing a reporting error can raise your score can increase 10-30 points in a month . Larger, persistent progress takes a number of months of consistent good behaviour.
4. Does checking my own CIBIL score lower it?
No. Checking your own score is a "soft enquiry" and has no impact on your CIBIL score. Only "hard enquiries," made when lenders check your report for a loan application, can affect it slightly.
5. Can I improve my CIBIL score without taking a new loan?
Yes. For example, you can improve your score without borrowing more money, by paying existing dues on time, maintaining low credit utilisation and fixing inaccuracies in your report.
6. How often does CIBIL update my credit score?
Most lenders provide data to CIBIL once a month. So your score is updated once a month. The day of the month depends on when your bank or lender reports.
7. Does paying off a loan early improve my CIBIL score?
Paying a loan early or on schedule usually helps, particularly if it improves your credit mix and lowers the debt you owe. But cancelling your single long-term account early can limit the length of your credit history.
8. What is the ideal credit utilisation ratio to increase CIBIL score fast?
Keeping utilisation below 30% of your total credit limit is ideal. Lower utilisation, closer to 10%, tends to reflect even more positively on your score over time.
9. Can errors in my credit report lower my CIBIL score?
Yes. Incorrectly reported late payments, incorrect account information, loans you don’t actually have – all of these can hurt your score. A lot. And unfairly. Regularly checking your report helps you spot these problems before they become serious.
Conclusion
Moving your credit profile from fair to excellent isn't about one big move — it's about consistency. To boost CIBIL score from 600 to 750, focus on basics: timely payments, modest utilisation, avoid superfluous credit applications, and keep an eye on your report periodically.
Start applying these seven steps today, and you'll likely see steady, measurable progress within a few months. Your future loan approvals — and the interest rates that come with them — will thank you.